


The Delaware Appraisal Clause in Plain English
A sentence-by-sentence walk through the appraisal paragraph found in most Delaware homeowners and commercial policies.
Independent claim appraisal · New Castle · Kent · Sussex
Your insurer agreed the damage is covered, then sent a number that won’t pay for the repair. Delaware Insurance Appraiser builds an independent, line-by-line valuation and carries it through the appraisal process written into your policy.
Covered isn’t the same as paid
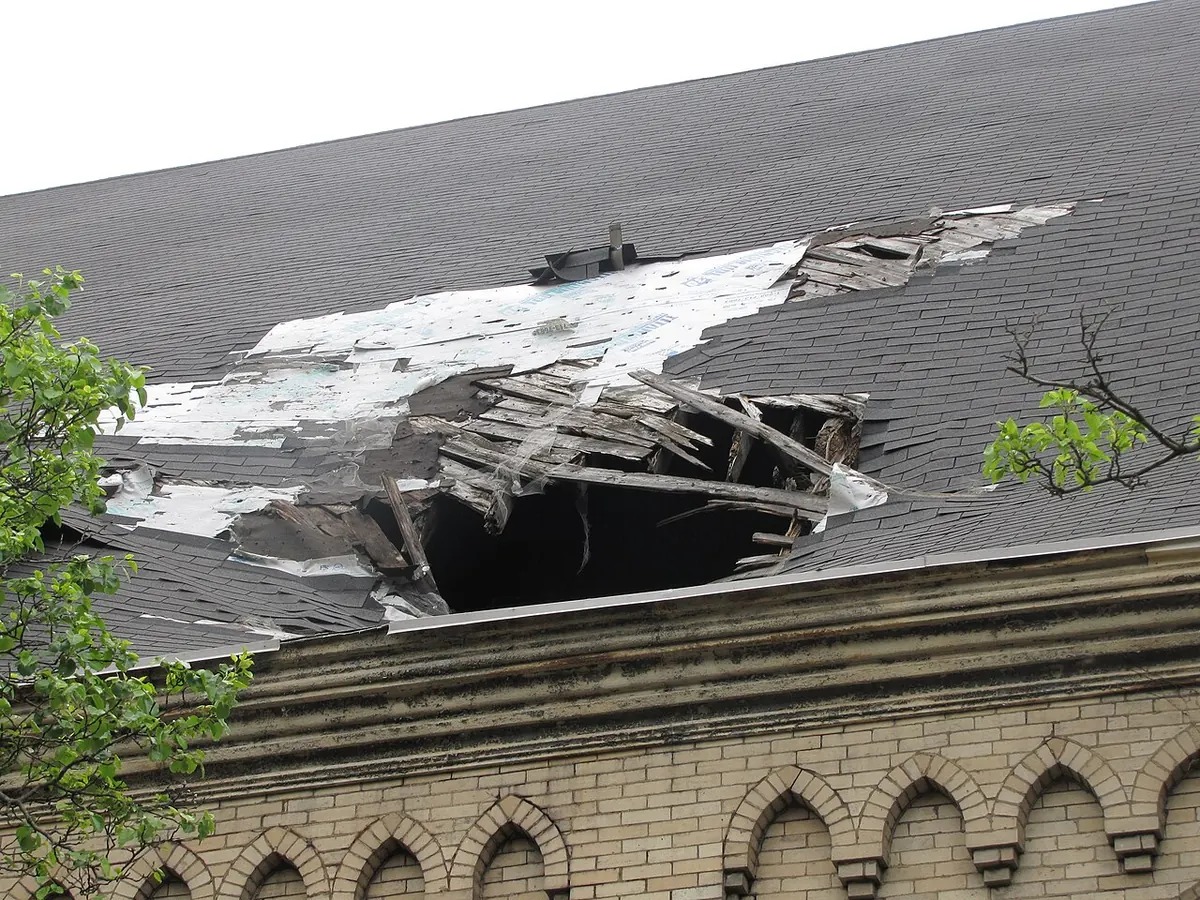
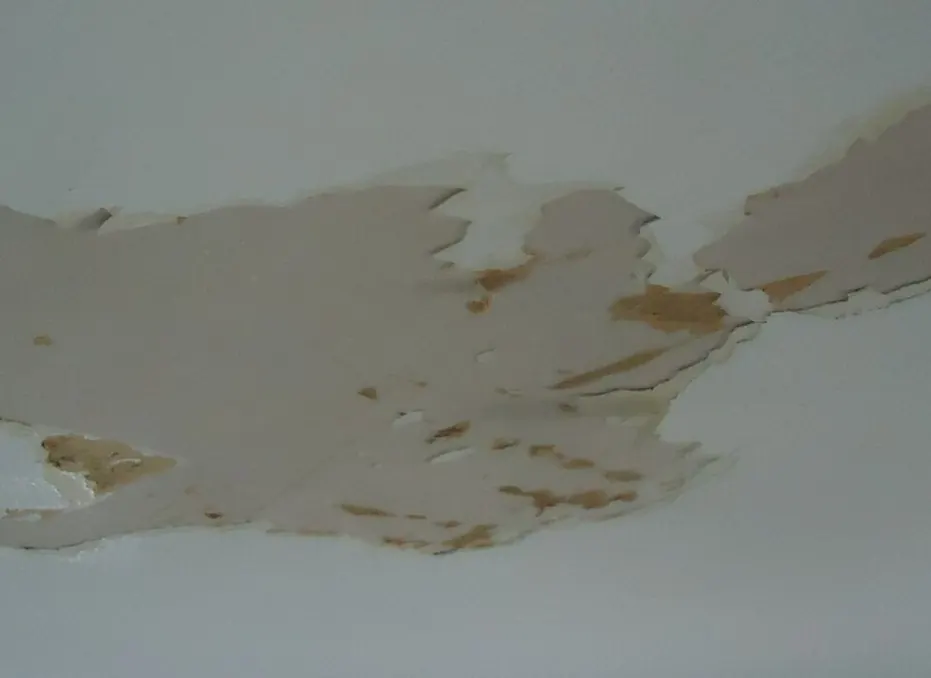
Most disputed claims in the First State aren’t denials. They’re short: a roof approved for repair when the shingles can’t be matched, a water loss scoped for one room when the floor runs through three, a coastal home where wind damage was written off as flood. A Delaware Insurance Appraiser exists for the gap between “covered” and “paid in full.”
When either side invokes the appraisal clause, Delaware Insurance Appraiser can be the appraiser you name. We inspect the property ourselves, price the repair for your town — Wilmington labor isn’t Seaford labor — and work line by line with the insurer’s appraiser until the numbers meet or an umpire decides.
Hired by youNever by the insurer on your claim
Three counties, three claim climates
Delaware is small — just three counties — but a rowhome fire in Wilmington, a hail-damaged roof in Dover and a wind-versus-flood fight in Bethany Beach are different claims. Pick a county to see what we look for there.
Delaware’s most populous county runs from the Pennsylvania line and the Brandywine Valley down past the Chesapeake & Delaware Canal. Rowhomes, stone houses and Riverfront condos in the north give way to fast-growing subdivisions in Middletown and Townsend.
Wilmington · Newark · Middletown · Bear
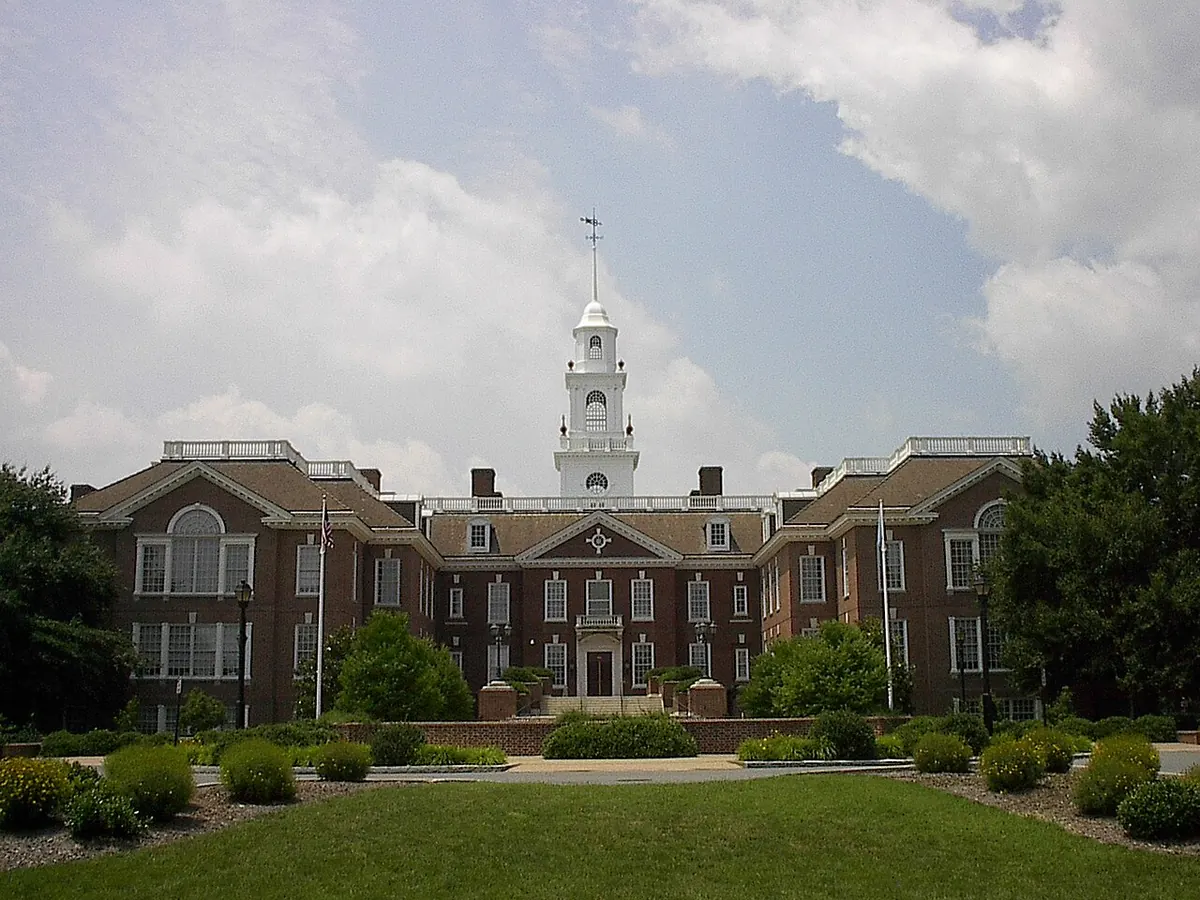
The middle county centers on Dover, the state capital, with farmland and Delaware Bay marshes on its eastern edge. Open country lets summer squall lines and tropical remnants build, and Dover Air Force Base means many military households.
Dover · Smyrna · Milford · Camden
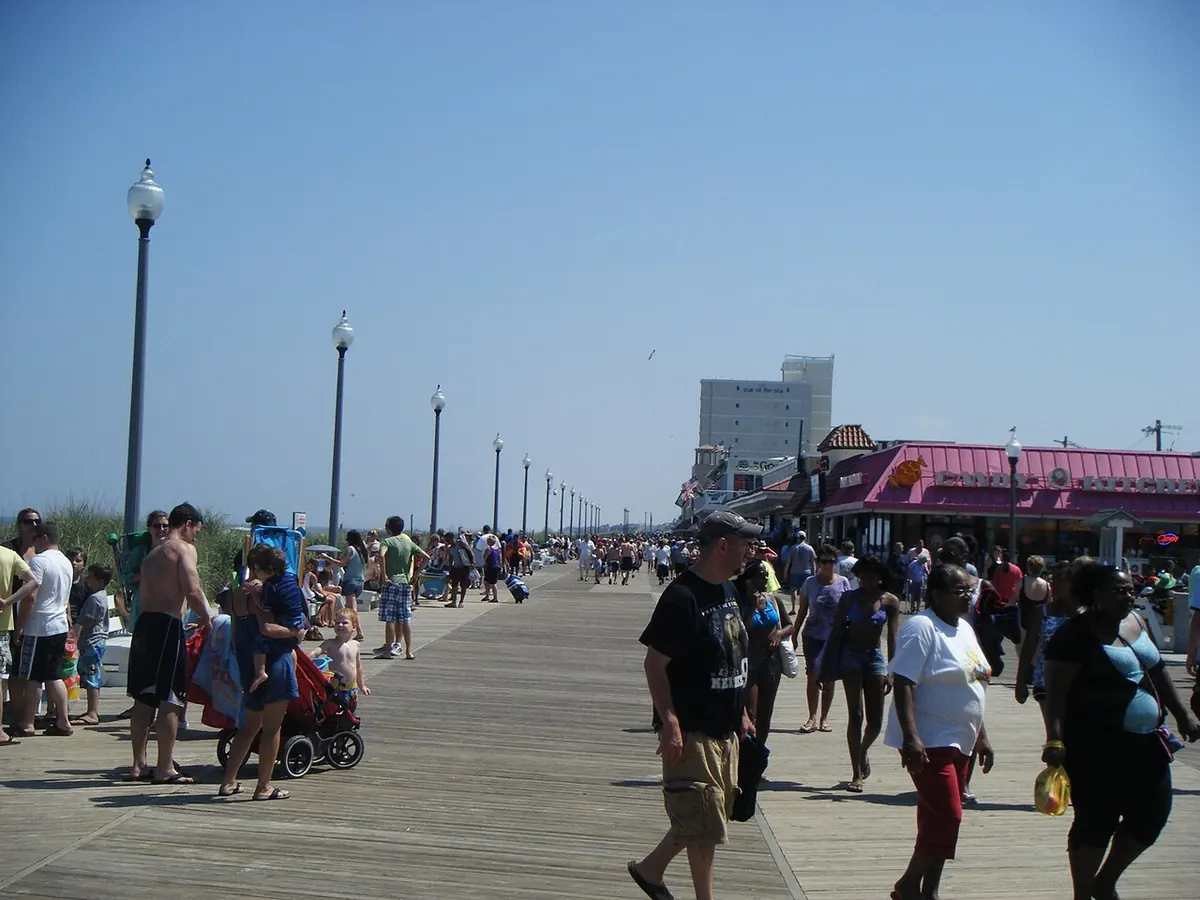
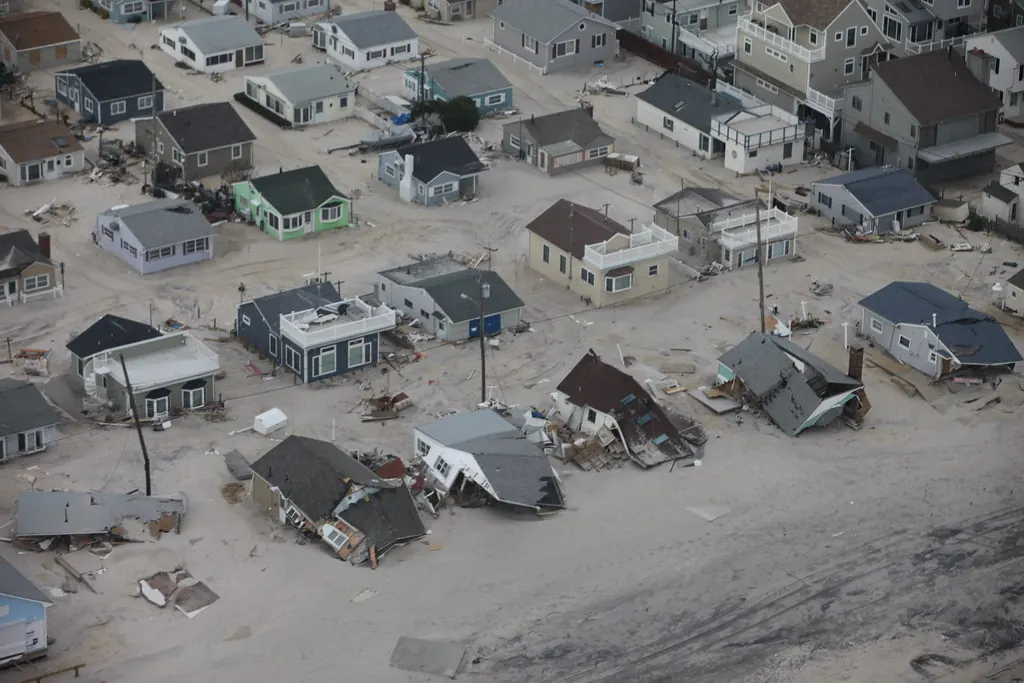
The largest county by area holds Delaware’s Atlantic beaches, the inland bays and a deep agricultural interior. Coastal Sussex faces nor’easters, named storms and wind-versus-flood questions; western Sussex sees poultry houses, farms and river towns.
Lewes · Rehoboth · Bethany · Georgetown · Seaford
Appraisal & estimating
Eleven services built around one job: a valuation of your loss that stands up in front of an appraisal panel. Start with an estimate review, or bring us in once appraisal has been demanded.
Quick check
Enter the two numbers you already have. A large gap is worth a conversation with a Delaware Insurance Appraiser; a small one is often closed faster with a documented supplement.
The full claim gap and fee estimator subtracts appraiser and umpire fees so you can see a realistic net figure. All figures are illustrative.
All 7 free worksheetsThe appraisal roadmap
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here’s how Delaware Insurance Appraiser moves a file from the first call to the award.
Read the full roadmapCoverage is accepted, but the amount isn’t. Gather the carrier’s full estimate, your contractor’s estimate, photos and the policy.
Either side can invoke appraisal in writing, as the policy describes. Name your appraiser and keep proof of delivery.
Each party chooses a competent, impartial appraiser, usually within a window the policy sets (often 20 days).
The two appraisers agree on a neutral umpire. If they can’t, a court can usually be asked to appoint one.
Each appraiser inspects and builds or reviews a line-item estimate of the loss.
The appraisers meet, compare line items and agree on as much as they can.
Storm record
Direct hurricane landfalls are rare here. Nor’easters, tropical remnants and summer storms are not. A Delaware Insurance Appraiser has to know how each one shows up on a roof, a wall and an estimate.
A slow nor’easter lingered for several tide cycles in March, battering Rehoboth, Bethany and Fenwick and reshaping the coastline.
Gloria raced up the coast in September, bringing wind damage and power outages across the state.
Isabel’s surge and wind affected the Delaware Bay shore and coastal communities in September.
February storms brought record seasonal snow to northern Delaware, with roof and ice-dam claims.
Sandy flooded bayfront and inland-bay communities and damaged dunes, roads and beachfront property.
Isaias produced tornadoes in Delaware in August, including a long-track twister through Kent and New Castle counties.
Ida’s rain pushed the Brandywine to record levels in Wilmington in September, flooding homes and businesses.
Free & private
Run the numbers before you call anyone. Every worksheet runs in your browser — nothing you type is stored or sent.
 Estimator
 Calculator
 Calculator
 CalculatorPlannerChecklist
Statewide, on site
We inspect in person in every town in all three counties. These are the communities where Delaware Insurance Appraiser handles claims most often.
Choosing help
Each solves a different problem. Picking the right help first saves time and fees — and a Delaware Insurance Appraiser should tell you when appraisal is the wrong tool.
| Question | Appraiser (us) | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Value the amount of loss | Prepare & negotiate the claim | Legal disputes & lawsuits |
| Best stage | Coverage accepted, amount disputed | Early, from first notice | Denials, deadlines, conduct issues |
| Result | Binding award (2 of 3 signatures) | Negotiated settlement | Settlement or judgment |
| Decides coverage? | No | No | Argues it in court |
FAQ
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work with the insurer’s appraiser and, if needed, present unresolved items to a neutral umpire.
A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the insurer’s estimate, and the gap between it and your contractor’s number is meaningful — generally more than several thousand dollars or about 10%.
Yes, on the amount of loss, once any two of the three panel members sign. That’s why your documentation should be solid before appraisal is invoked.
Each side pays its own appraiser and usually half the umpire. We put our fee in writing before any work begins, and the first conversation is free.
Yes — all three counties. We regularly work in Wilmington, Newark, Bear, Middletown, Dover, Smyrna, Milford, Georgetown, Seaford, Lewes, Rehoboth Beach and Bethany Beach.
Appraisal journal
Practical guides on policy language, coastal storms and documentation, written for Delaware property owners.
A sentence-by-sentence walk through the appraisal paragraph found in most Delaware homeowners and commercial policies.
Homeowners policies cover wind; flood policies cover rising water. Here’s how to document both after a storm at the bay or the beach.
Each professional solves a different problem. Picking the right one first saves time and fees.
Start with a conversation
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing — no pressure, no obligation.